 Roof
Roof life
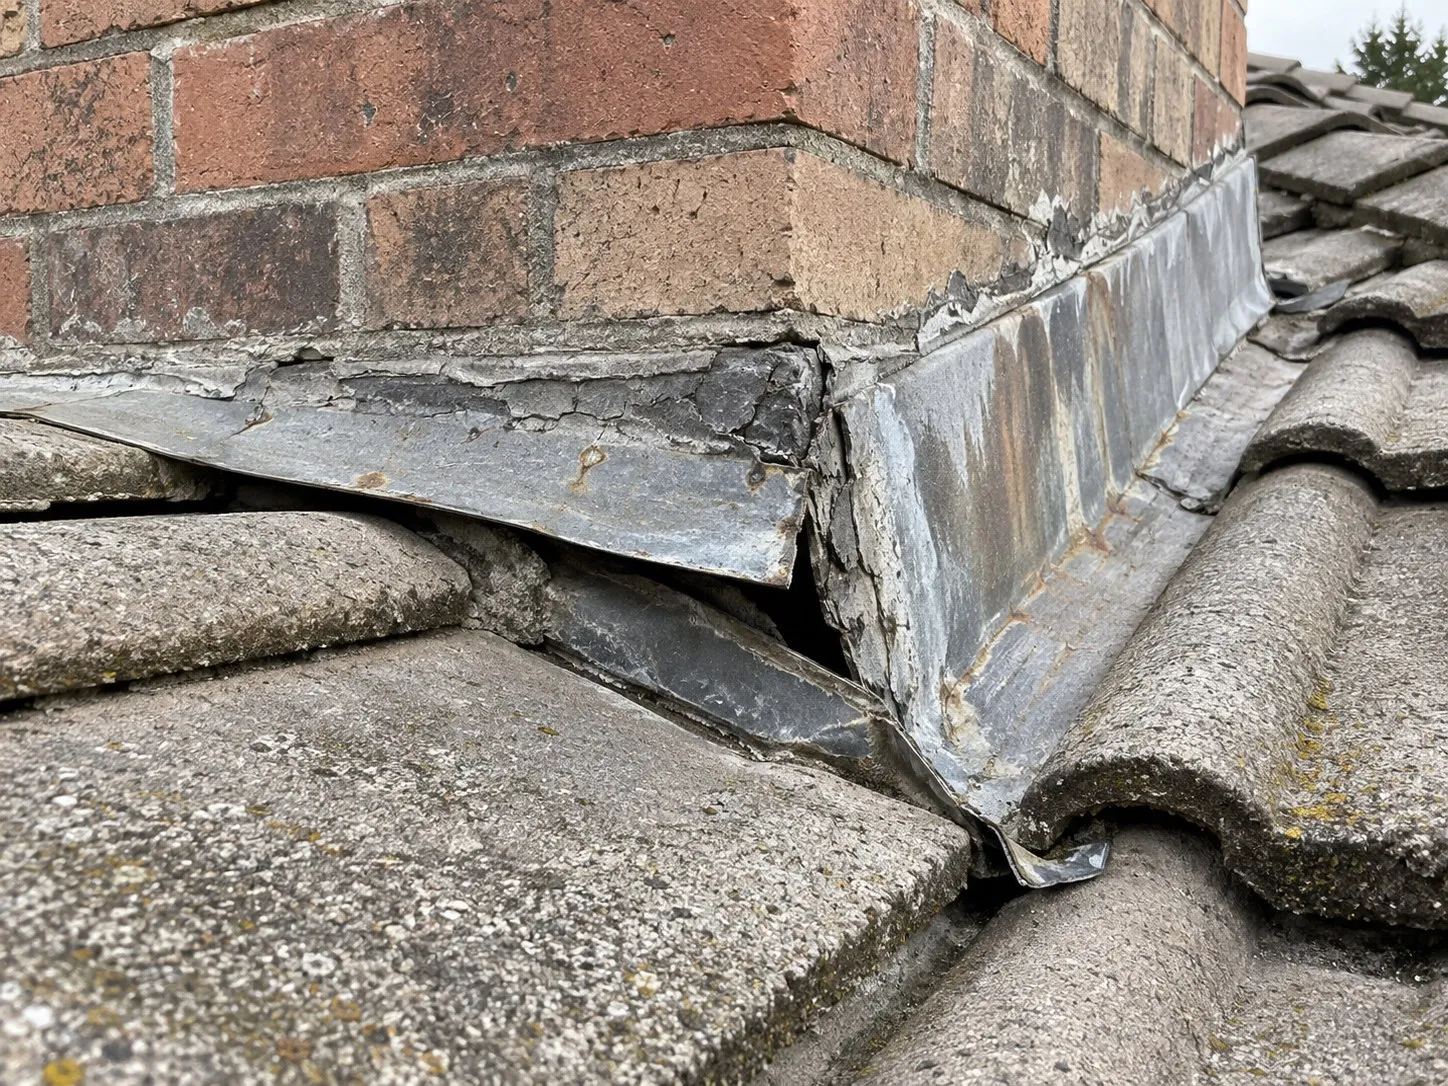
A roof needs enough remaining service life to pass. Visible wear, missing tiles and lifted flashing at the valleys all get called out.
Navigation
 Buy
 Photo unavailable8939 Mango P-$59,901Listing brokerageWILLS ESTATE BROKER
 Photo unavailable16600 Terrace F-$39,996Listing brokerageWILLS ESTATE BROKER
 Sell
 Photo unavailable14394 HillcrestComing SoonListing brokerageCENTURY 21 SYNERGIA REALTY
 Photo unavailable8755 TangeloActive Under ContractListing brokerageRE/MAX One
 InvestPhoto unavailable8939 Mango P-$59,901Listing brokerageWILLS ESTATE BROKERPhoto unavailable16600 Terrace F-$39,996Listing brokerageWILLS ESTATE BROKER
 Inspector’s Eye
 Vault
 Learn
 AboutTalk to Zarko
VA buyers
Zero down is the easy part. The house has to pass too — and that is where a VA offer in Fontana is won or lost.
 Zero down
 Appraisal read
 Condition rules
Value and the minimum property requirements are checked in the same visit. These are the four systems that stop a Fontana file.
See the inspector’s eye →RoofA roof needs enough remaining service life to pass. Visible wear, missing tiles and lifted flashing at the valleys all get called out.
 Electrical
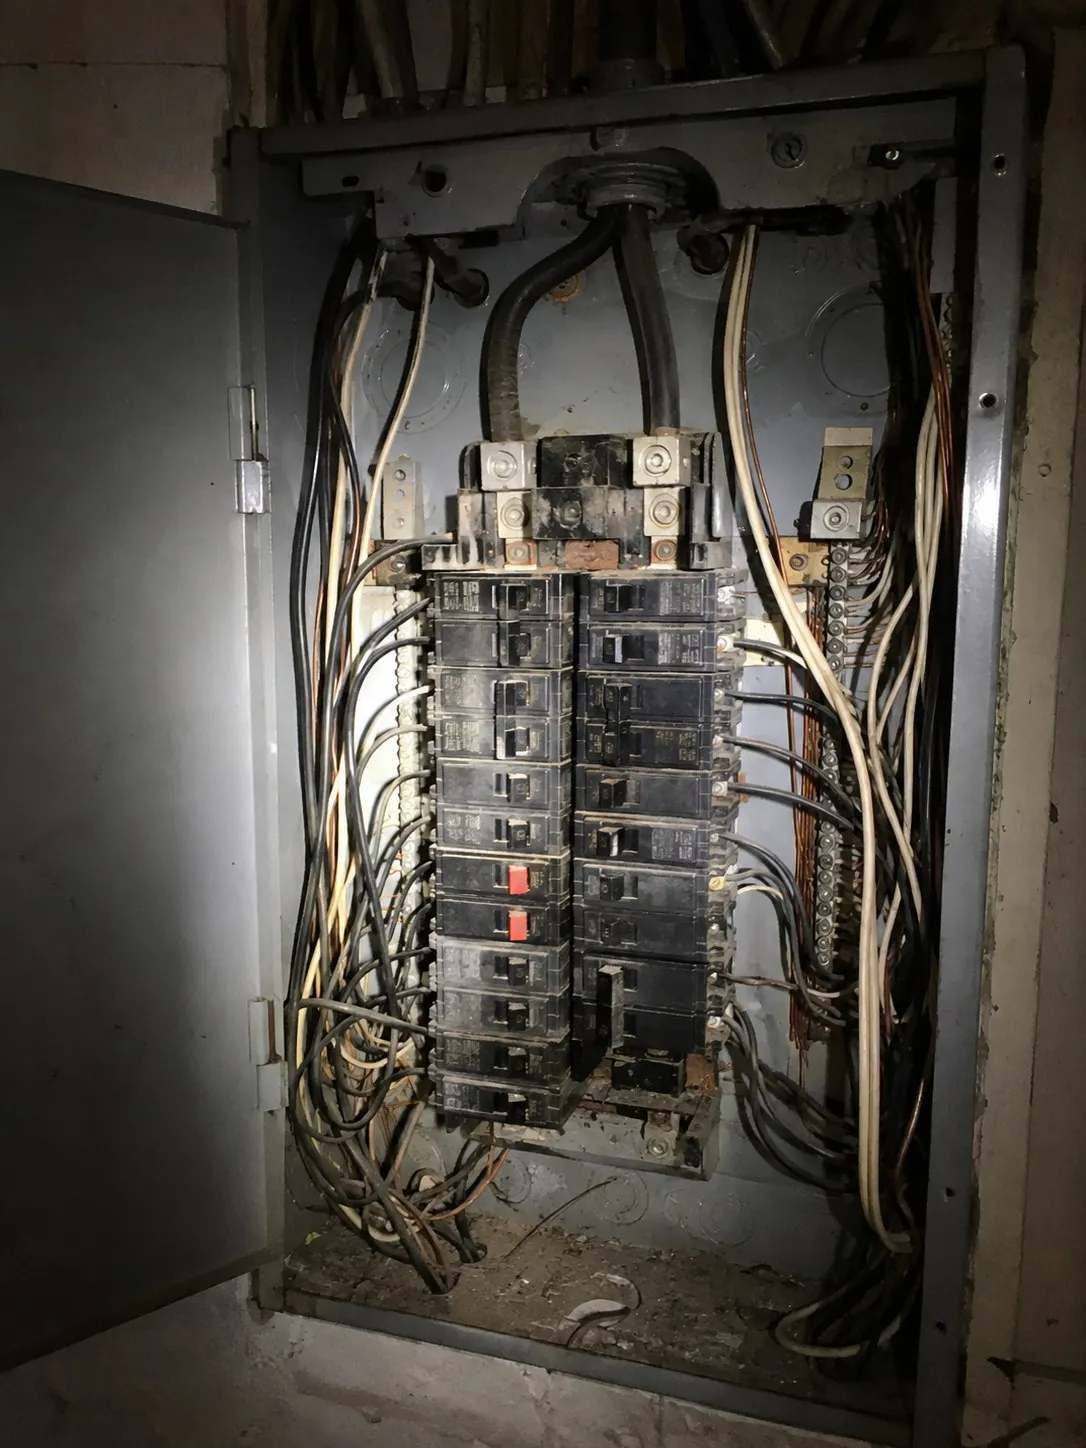
Heat, power and hot water have to be safe and functional on the day of the visit. A panel with known hazards is written up, not waved through.
 Plumbing
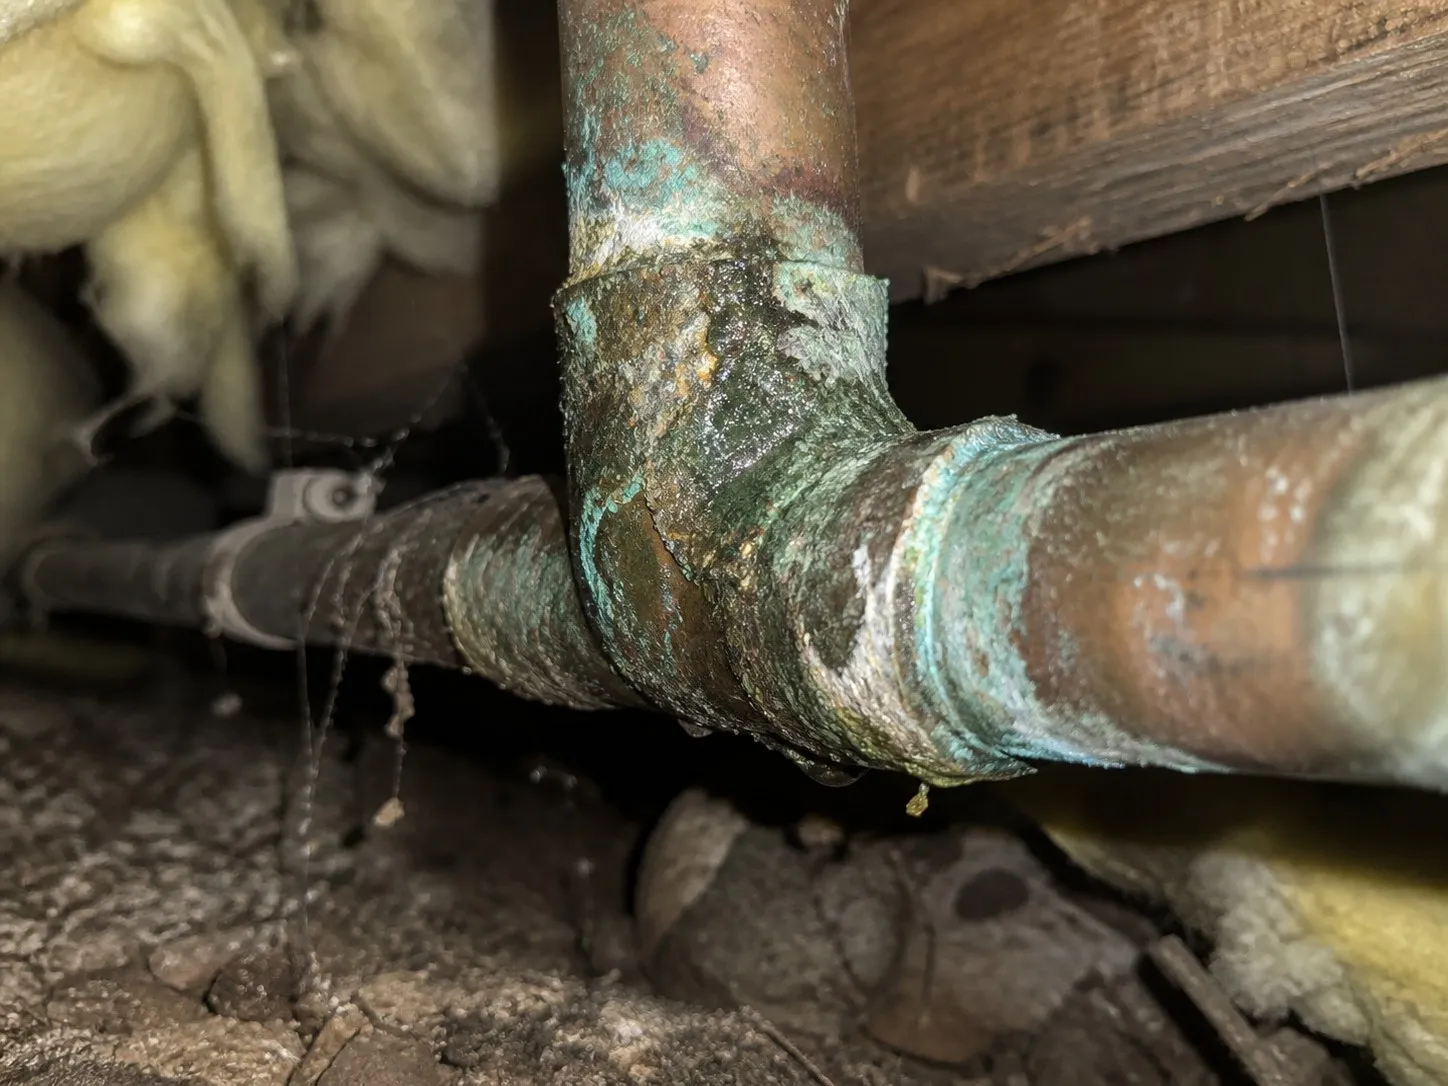
Corrosion at the joints means water is already moving where it should not. An active leak is a repair the file has to clear.
 Site
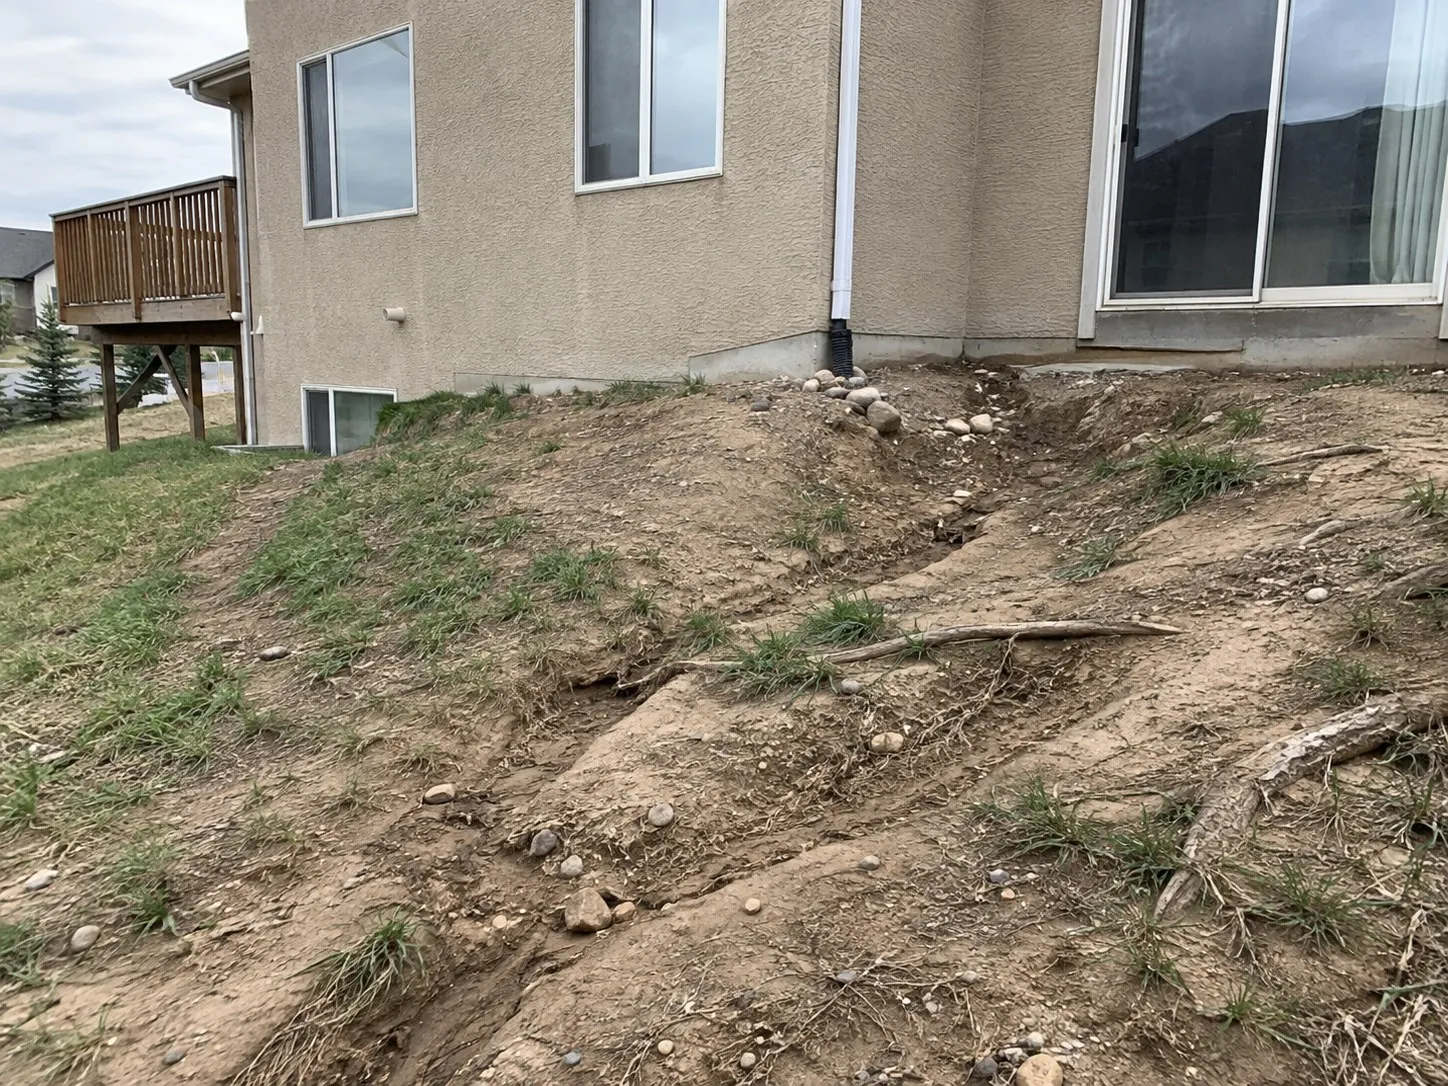
Standing water and ground that falls back toward the slab are site conditions, and site conditions are inside the appraiser’s brief.
 Peeling paintAny peeling, chipping or flaking paint, especially on homes built before 1978.
 Water heater strappingCalifornia requires the water heater to be strapped for seismic safety, and the appraiser checks it.
 Pest clearanceActive wood-destroying pest or fungus findings need clearance before the loan can close.
 Safe accessWalkways, railings and steps need to be sound and free of trip hazards.
Photos are illustrative of the condition item, not photographs of a specific address.
Active listings in Fontana right now. VA eligibility is confirmed on the read — send me one and I check the condition items before you write.
Open the city page → New
4 beds2 baths1,495 sq ft
$645,000
Nation One Realty Group Corp
 New1 day
4 beds3 baths2,483 sq ft
$690,000
Prime Impact Real Estate
 New1 day
3 beds2 baths1,366 sq ft
$649,999
The One Luxury Properties
 New1 day
3 beds2 baths1,554 sq ft
$599,999
COLDWELL BANKER LEADERS
 New1 day
4 beds3 baths1,556 sq ft
$685,000
DYNASTY REAL ESTATE
 New1 day
4 beds3 baths1,996 sq ft
$725,000
Anvil Real Estate
Active listings, as of September 22. Photos are illustrative Fontana street scenes, not photographs of the address on the card.
Four steps from eligibility to keys, in the order they actually happen.
Start with the read →
Your Certificate of Eligibility, and a lender who writes VA loans every week. There is no private mortgage insurance on a VA loan, so the monthly number starts lower than the same price on a conventional file.

Send me the listing before you write. I read the photos and the disclosures for the condition items a VA appraiser calls out, so the offer is built around them instead of being renegotiated later.

The VA assigns the appraiser. Value and the minimum property requirements are checked in the same visit, and anything flagged has to clear before the loan can fund.

The VA guarantees a portion of the loan, and most eligible veterans still hold their full entitlement. A one-time funding fee helps sustain the program and can be financed into the loan rather than paid at the table.
With nothing down, the cash you bring is closing costs. This is the lever that moves them.
Selling to a VA buyer? →
Sellers can contribute toward allowable closing costs and prepaid items on a VA loan. With nothing down, that contribution is the number that decides what you actually bring — and it is negotiated in the offer, not discovered at the end.

VA buyers are motivated and qualified. Simple repairs, clear documentation and a little preparation can make the difference between a limited audience and a strong, on-time offer that closes.
Negotiated this week in Fontana
Bought by: I follow these closings myself — some of these buyers I know, a few were my clients. The names are for Vault members; everything else on the row is open.
Real Fontana rows, as of September 22. What each side conceded is not public; the buyer’s details are released to registered Vault members.
Experience makes the difference
I read your listing myself, apply 20+ years in Fontana, and tell you what a VA appraiser is likely to write up — before you spend an appraisal fee finding out.
Zarko Maletin Broker & founder DRE #02038779 InterNACHI certified inspector